Medically Reviewed by: Alyssa DeStefano, LCSW, Licensed Clinical Social Worker | Revolution Recovery Center
You finally decided to get help. You called a treatment center, did the intake, maybe even threw a bag in a car and headed to treatment, and then – hello letter – insurance has denied your coverage for rehab. It’s frustrating, it’s confusing, and it’s honestly a little scary when you or a loved one is ready for healing and that’s the answer you get. But here’s the truth: a denial is NOT the end of the road. Insurance companies deny claims every single day, and many of those decisions are successfully appealed when you know the right way to fight back. You have rights. You have options. And you do not have to go through this alone. Let’s talk about what it really means to be denied and what’s next.
Why Insurance Companies Deny Rehab Coverage in the First Place
Knowing the “why” helps you when fighting against the “what.” Most of the time insurers do not refuse treatment without providing an explanation. Here are some of the most popular ones:
- Lack of medical necessity: The insurance company has determined your condition is not one that necessitates the type of care you are requesting-residential treatment instead of outpatient treatment.
- Out-of-network provider: The plan doesn’t have a contract with the facility.
- Missing pre-authorization: The necessary approval was not secured prior to the admission.
- Incomplete paperwork: A missing form, code, or note from the doctor could cause a denial.
- Plan exclusions or limits: Your plan may have a limit on the number of days for which you are covered or limit certain services.
Many of these are fixable, which is good news.
Read Your Denial Letter Carefully Before Doing Anything Else
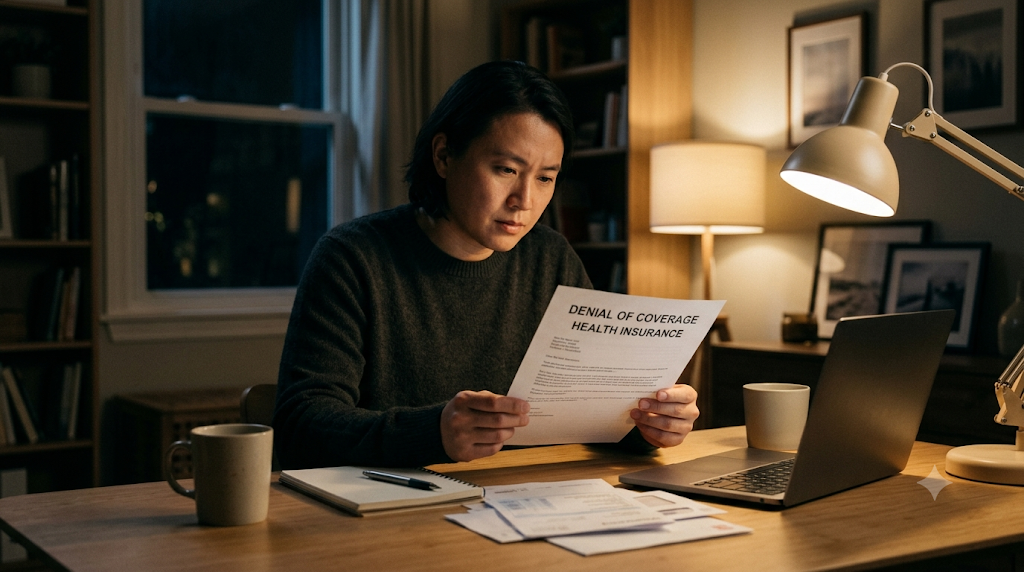
Don’t throw the letter away in frustration, it is your road map. It must include the specific reason for denial, the clinical criteria applied, the time to appeal, and how to do so. Highlight the specific language that was used as a reason, and keep track of each date listed. The appeal period can be as short as 180 days, and most of the urgent care situations can have much shorter time periods.
Ask for a Peer-to-Peer Review With Your Doctor
A peer-to-peer review is a dialogue between your doctor or clinician and a medical reviewer at the insurance company. It’s one of the quickest tools for winning an appeal because your doctor can explain, in clinical language, what you require. Request this right up front through your provider. It’s not a formal appeal, but it clears up the issue within days, not weeks.
File an Internal Appeal With Strong Supporting Documents
If the denial is upheld, you can lodge a formal internal appeal which is where the insurer will reassess their decision. A successful appeal generally involves:
- A note from your doctor or therapist outlining your diagnosis and history as well as the reason why the treatment is necessary.
- Document previous treatment, especially previous attempts at lesser levels of care, periods of relapse, hospitalizations, ER visits.
- Clinical evaluations – like those developed using ASAM criteria – that providers often rely on to determine appropriate care levels.
- Your personal statement on how consuming substances is impacting your life, work and relationships.
Focus on the point listed in the denial. Tell the insurer how your documents support the claim. For example, if the insurer denied treatment as not needed, your documents should have provided the evidence.
Request an External Review If the Appeal Fails
If you lose your internal appeal, you have other choices. The Affordable Care Act mandates external reviews for most health insurance plans. An outside third party who is not connected with the insurance company reviews the claim and if they find in your favor, the insurance policy is supposed to accept the outcome. Your denial letter will tell you how to request an external review. You can also call your state department of insurance for assistance.
Know Your Rights Under Mental Health Parity Laws
Under the law, such as the Mental Health Parity and Addiction Equity Act, most health plans that offer addiction coverage are expected to cover it as thoroughly as they do medical and surgical coverage. An insurance company is unlikely to restrict coverage, raise the cost or make approval more difficult for addiction treatment than it does for something like a heart condition or back injury. If you feel your plan is not treating rehab fairly, bring it up in your appeal.
Explore Other Ways to Pay for Treatment While You Wait
Appeals are slow, but your injury can’t wait: In the meantime, while your claim is pending, find out from your treatment provider:
- Flexible payment options or pay-what-you-can fee schedule
- Financing options designed for healthcare costs
- Free or low-cost, state-funded or nonprofit programs offering low-cost or free treatment
- Different levels of care, such as outpatient or partial hospitalization, while the appeal is pending
- Employee assistance programs (EAPs), which can include brief therapy or referrals
Beginning some type of care today is preferable to waiting for the ideal approval.
Don’t Let a Denial Stop Your Recovery
A denial letter can be a crushing blow, but most will find it more like a locked door with a few keys inside: peer-to-peer review, internal appeal, external review, and legal rights. The work can take time and paperwork, but it is worth it. Not sure how to start? The team at Revolution Recovery Center can help you check your benefits, understand your denial, and determine your options so you can concentrate on healing, not red tape. Call today – your recovery depends on it.
Contact details
- Company name – Revolution Recovery Centers
- Corporate Address – 415 S. Federal Highway, Boynton Beach, FL 33435
- Call Now – (866) 890-7286 24/7 Support Available
- Email Address – info@revolutionrecovery.com
FAQs
My insurance just denied rehab coverage. What should I do first?
Breathe, then spend time reading the denial letter carefully. Here you’ll find the reason you were denied, the rule the insurance used to make that denial, and the deadline for your appeal. After you identify the reason, call your care provider and see if they can file a peer-to-peer review – that’s the fastest way to get a denial overturned.
Does a denial mean I can’t get treatment at all?
No. A denial simply indicates that the insurance company won’t cover the claim based on the information they have today. The request can be appealed, challenged with an external review, or paid out of pocket as you wait. Sometimes the individual has treatment at the time of the appeal, or even begins treatment at a lower level of care, while the appeal is ongoing.
How long do I have to appeal?
It varies from plan to plan but most permit 180 days from the date of the letter. Some urgent situations where waiting may cause harm to health can get things processed much more quickly. Look at the date on the letter and submit it as early as possible, because the longer you wait the worse it gets.
What’s a peer-to-peer review, and do I need one?
It’s a conversation between your provider and a medical reviewer at your insurer. Your provider will tell the reviewer why this treatment is medically necessary. Sometimes, that’s enough to change a denial so you don’t need to do anything else, but don’t be shy about asking – it can be done in days, not weeks.
What should I include in my appeal?
There are generally four components to a good appeal: a medical necessity letter from your doctor or therapist; your course of treatment, including your history of treatment, relapses, or any admissions to the hospital; clinical evaluations; and a brief personal letter explaining your case. Answer specifically to the reason given by the insurer. If they said you didn’t need treatment, your paper should prove otherwise.
What if my internal appeal gets denied too?
You can often appeal for an external review, where an independent person makes a decision rather than your insurer. If they side with you, your insurance company is likely to have to accept that. You can also get advice from your state’s department of insurance, or file a complaint with them.
Can my insurance really treat addiction treatment differently from other medical care?
Probably not. The Mental Health Parity and Addiction Equity Act generally prohibits plans that cover substance use treatment from imposing more restrictive quantitative and nonquantitative treatment limits on mental health than on medical or surgical services. If you believe they are, include “parity” in your appeal.
What if I’m out of network? Is that an automatic no?
Maybe not. Your plan might provide out-of-network coverage at a reduced rate, or allow you to go out of network if none of the in-network alternatives will do. Check with the insurer; if you have a letter from the doctor supporting your decision, that can help.